How Much Money Can I Get From a Reverse Mortgage
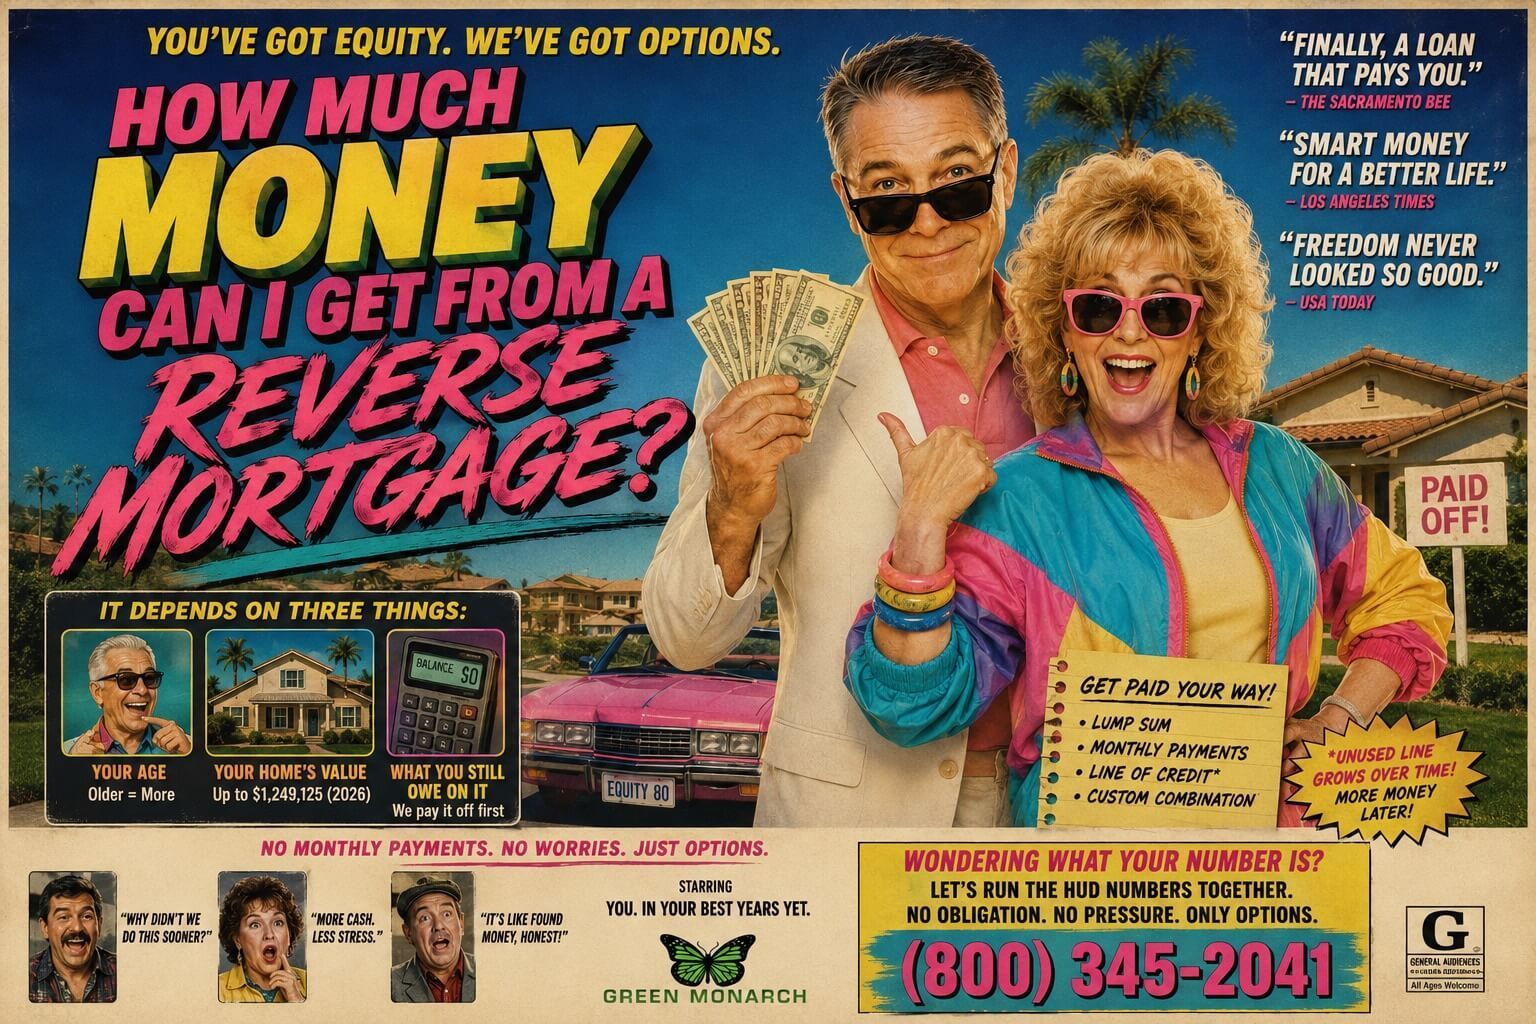
The answer to the question of how much money can I get from a reverse mortgage depends on your age, home value, existing mortgage balance and current loan calculations.
There is no single dollar amount or percentage that applies to every California homeowner.
For a Home Equity Conversion Mortgage, commonly called a HECM, the amount available is calculated using federal program guidelines. Your individual numbers determine how much of your home's value may be available through the reverse mortgage.
Three factors are especially important:
- Your age
- Your home's value
- What you still owe on your home
Interest rates also affect the calculation, which is one reason estimates can change over time.
Let's look at what each of these means for you.
How Does Your Age Affect a Reverse Mortgage?
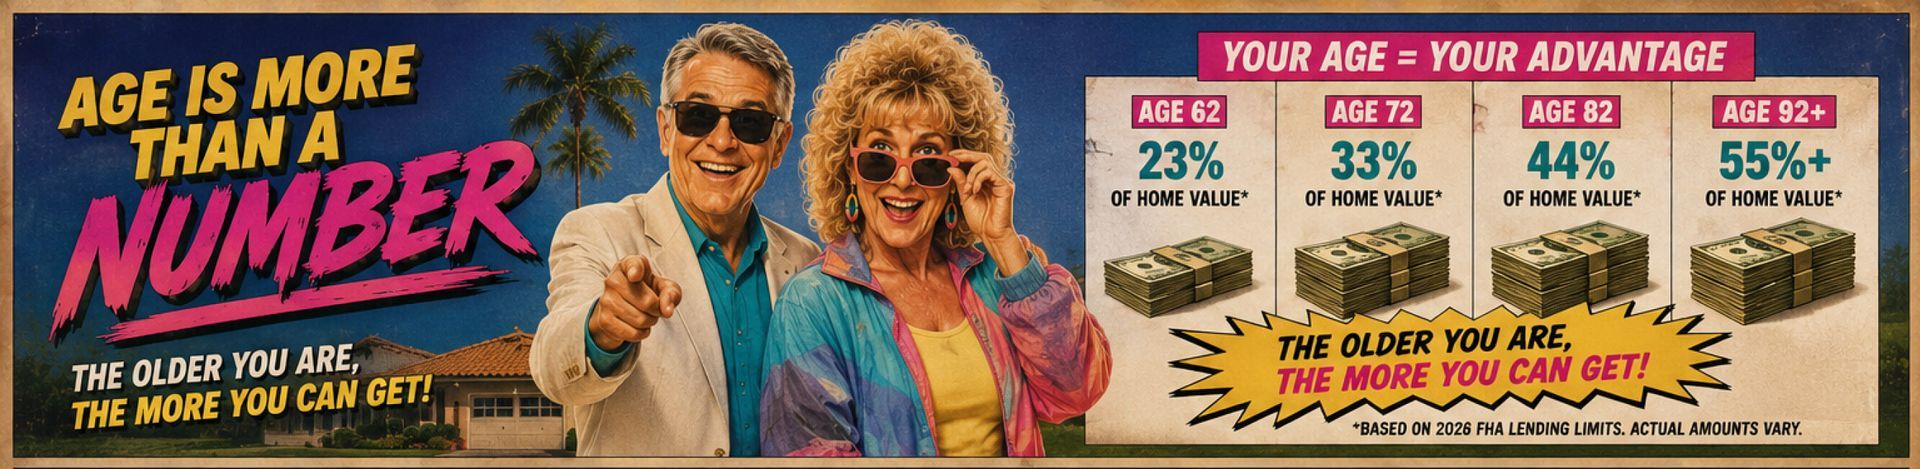
One of the first factors in determining how your age affects a reverse mortgage is the age used in the HECM calculation.
Generally, older eligible borrowers may qualify to access a greater percentage of the home's applicable value than younger eligible borrowers.
But age is not the only factor.
Interest rates also affect the calculation. Green Monarch's source material illustrates this with a 66-year-old borrower, showing how the percentage available could differ substantially under different expected interest-rate assumptions.
This is important if you have received estimates at different times.
A different number does not necessarily mean one lender is offering a better reverse mortgage than another. Changes in the rate environment can change the calculation.
How Does My Home Value Affect a Reverse Mortgage?
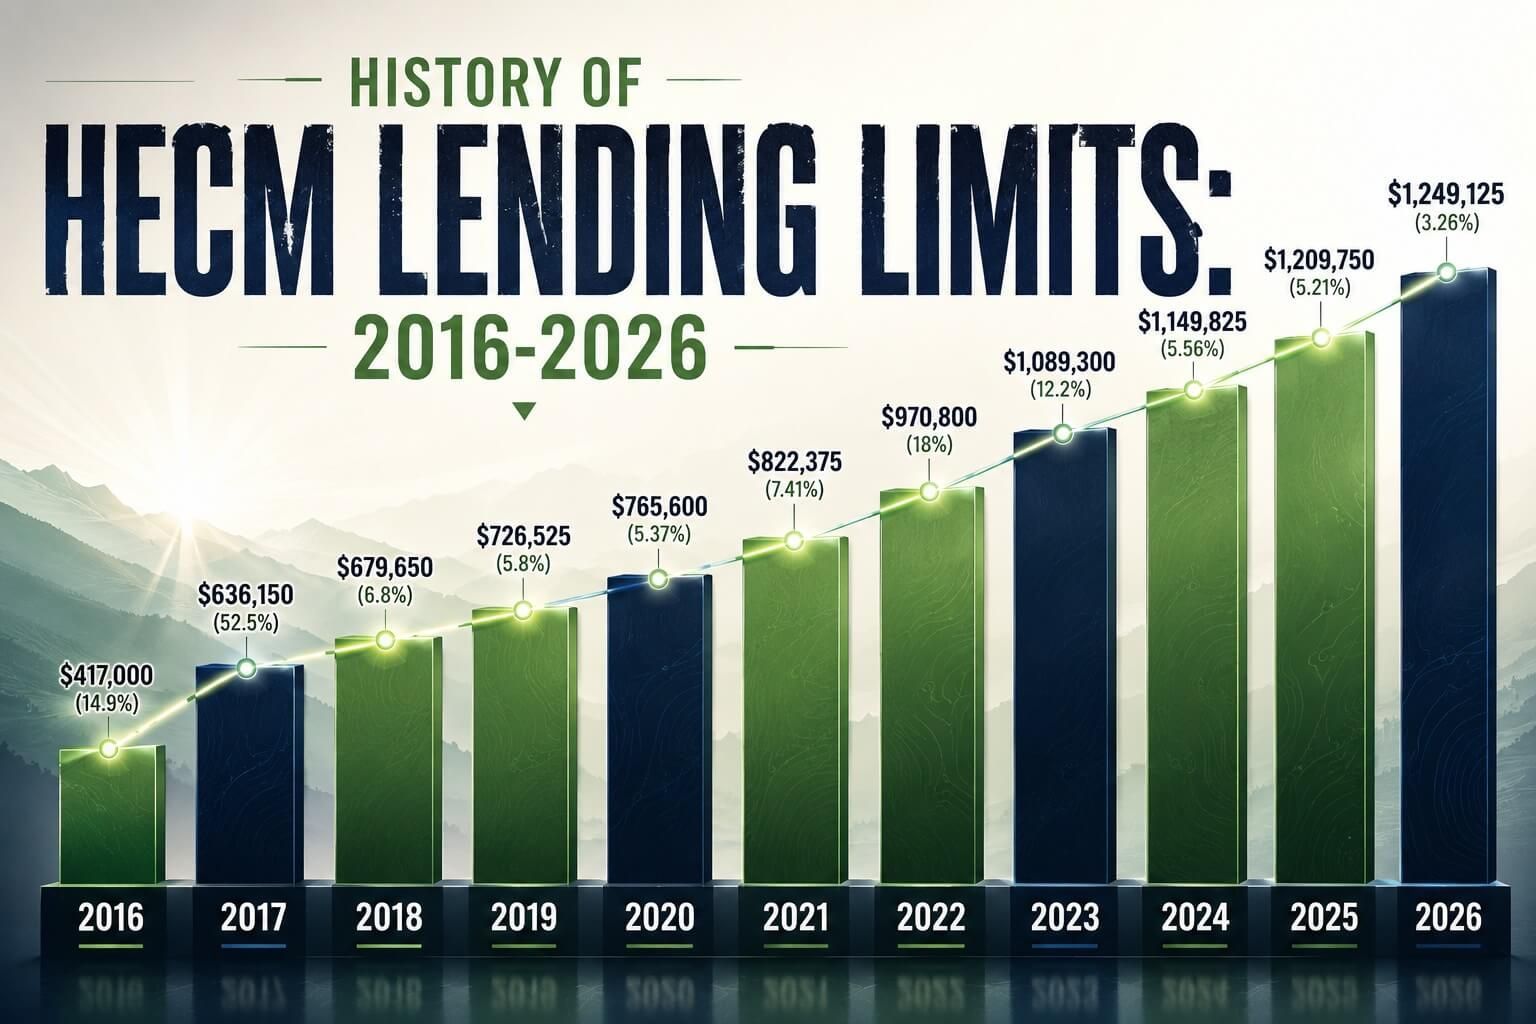
The amount your home value affects a reverse mortgage depends on both the property's value and the applicable federal HECM lending limit.
In general, a higher home value can potentially provide access to more equity, but only up to the value recognized by the HECM program.
Green Monarch's source material states that the 2026 HECM lending limit is $1,249,125. For a home valued above that amount, the HECM calculation does not simply continue increasing based on the property's entire market value.
This can be particularly relevant in California and Orange County, where some homes may exceed the HECM lending limit.
Homeowners with higher-value properties may also investigate whether a jumbo reverse mortgage is an appropriate alternative, but that is a different product and should be evaluated separately.
What If I Still Have a Mortgage on My Home?
If you have an existing loan, your current mortgage balance affects how much reverse mortgage money is left for you after that debt is addressed.
A reverse mortgage can be used to pay off an existing mortgage.
The existing mortgage balance is generally paid first from the reverse mortgage proceeds. The remaining available proceeds, if any, can then be structured according to the available payout options.
For some homeowners, this means the largest financial benefit may not be receiving a large amount of cash.
It may be
eliminating the required monthly principal and interest payment on the existing mortgage, while continuing to meet the reverse mortgage's requirements. Green Monarch's original material makes this distinction clear and also notes that homeowners with larger existing balances may receive more modest remaining cash proceeds.
Reverse Mortgage Cash Back Options
California homeowners considering
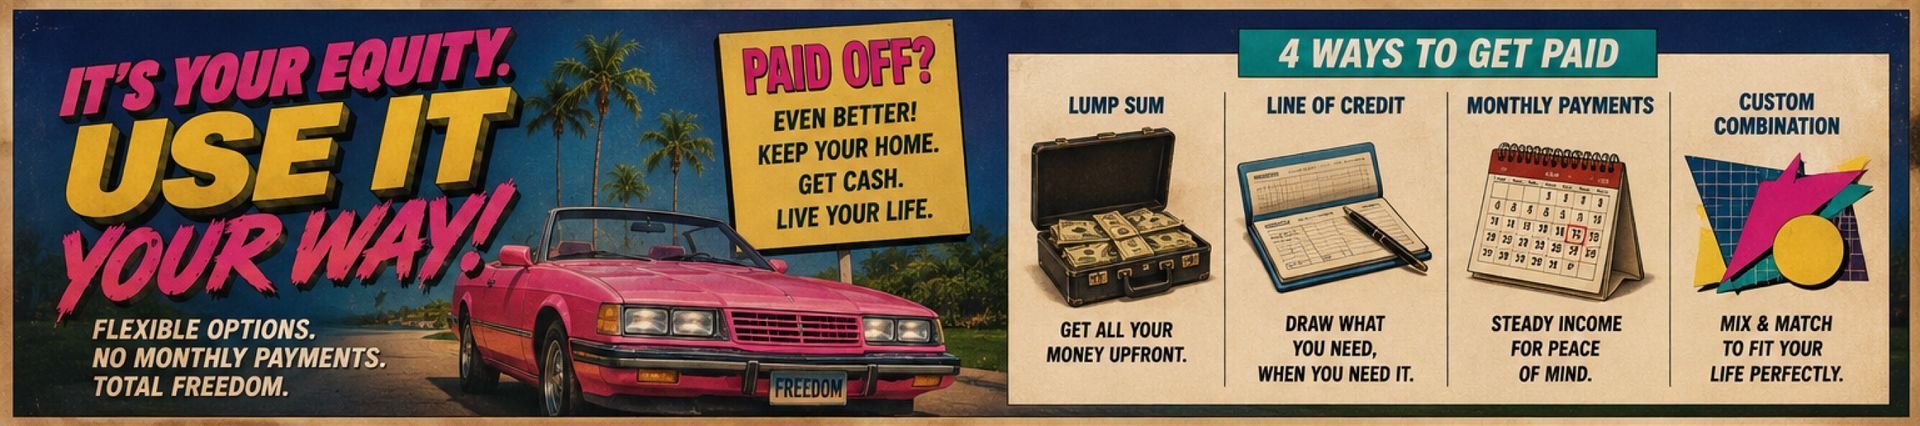
reverse mortgage cash back options have more than one way to receive available reverse mortgage proceeds.
Depending on the loan and the homeowner's circumstances,
the source material identifies four basic possibilities:
- Lump sum
- Monthly payments
- Line of credit
- A custom combination
The right structure depends on what the homeowner is trying to accomplish.
For example, one homeowner may want to eliminate an existing mortgage and maintain access to additional funds.
Another may be interested in monthly proceeds.
Someone else may prefer having a line of credit available rather than taking money immediately.
The important question is not simply, "How much can I get?"
It is also,
"How do I want the available money structured?"
Reverse Mortgage Line of Credit
One potential reverse mortgage line of credit feature is particularly important for homeowners comparing their payout choices.
According to Green Monarch's source material, the unused portion of a HECM line of credit can grow over time, potentially providing access to additional funds later.
That is one reason the line-of-credit option may appeal to homeowners interested in flexibility rather than receiving all available proceeds immediately.
A lump sum and a line of credit serve different purposes.
A lump sum provides available proceeds upfront.
A line of credit can provide access to funds as needed, subject to the loan's terms.
Neither option is automatically "better."
The better structure depends on
what you are trying to accomplish with your home equity.
Can I Get All My Home Equity From a Reverse Mortgage?
The answer to can I get all my home equity from a reverse mortgage? is no.
A HECM does not simply take your home's market value, subtract your existing mortgage and hand you everything remaining in cash.
Federal calculations determine the amount initially available.
As Green Monarch explains in its source material, the program deliberately limits the percentage of the home's applicable value that can be accessed.
So if your home has significant equity, your available reverse mortgage proceeds and your total home equity are not the same number.
That distinction is important when homeowners begin comparing options.
Average Cash Back From a Reverse Mortgage
There is no meaningful universal average cash back from a reverse mortgage that can tell an individual California homeowner what they will receive.
Two neighbors could own similarly valued homes and still qualify for very different amounts.
Why?
They may be different ages.
They may owe different amounts on their existing mortgages.
Their loans may be calculated under different interest-rate conditions.
They may also choose different ways of receiving the available proceeds.
Green Monarch's original article specifically cautions against presenting one "average" number because age, home value and existing mortgage balance can produce dramatically different results even for homeowners living on the same street.
That is why an individual calculation is far more useful than an industry average.
How Much Reverse Mortgage Money Will I Actually Receive?
To determine
how much reverse mortgage money you will actually receive, the calculation needs to move from general information to your specific circumstances.
Among the important pieces of information are:
- Your age.
Age affects the HECM calculation. - Your home's value.
The property's value is considered up to the applicable HECM program limit. - Your existing mortgage.
Any mortgage that must be satisfied reduces the proceeds remaining for other uses. - Interest-rate conditions.
Rates can affect how much may be available. - How you receive the proceeds.
Your options can include a lump sum, monthly payments, line of credit or an available combination of payout methods.
That is why an online article can explain how the calculation works, but it cannot responsibly tell every homeowner exactly how much money they will receive.
Your actual numbers have to be run.
Reverse Mortgage Options for California Homeowners
For homeowners comparing
reverse mortgage options in California, getting the largest possible amount of money should not automatically be the goal.
- Sometimes taking less may make more sense.
- Sometimes a line of credit may fit the objective better than a lump sum.
- Sometimes eliminating an existing monthly mortgage payment may be more important than receiving additional cash.
- And sometimes waiting may be worth considering.
Green Monarch's source material notes that the amount available to the same borrower can change as the borrower ages and as interest-rate conditions change. This is one reason Green Monarch says its conversations begin with education and with asking the homeowner what they are actually trying to accomplish.
The numbers matter.
What you want those numbers to accomplish matters just as much.
Wondering How Much You Could Get?
If you are asking how much money could I get from a reverse mortgage in California, Green Monarch can calculate your actual numbers based on your individual situation.
Their first question is not simply, "How much can you borrow?"
It is:
"What are you trying to accomplish?"
That distinction matters because the largest available amount is not necessarily the best choice.
Green Monarch can run the applicable numbers using the same HUD calculations used for HECMs and help you understand the available options. Its source material describes this approach as "no obligation, no pressure, only options."
Call
Green Monarch at (800) 345-2041 to discuss your situation and find out what your numbers may look like.